Retiring in Thailand can offer a comfortable lifestyle, an active social life and more choice about how you spend your time and money. But making it work long term takes more than finding an affordable home in a place you enjoyed on holiday. Your income, healthcare needs, permission to stay and everyday surroundings all need to fit together.
I’ve lived in Thailand for nearly 30 years, including around 25 years in Chiang Mai before moving to Hua Hin in 2024. This guide draws on that experience and my background in property to examine the decisions involved in settling here.
This guide covers the main decisions involved in retiring in Thailand, from realistic budgets and visa options to healthcare, housing and where to settle. It also looks at the compromises and longer-term arrangements worth considering before you commit.
Retirement in Thailand at a Glance
These five areas form the foundation of a retirement plan. The sections below explain each in more detail.
| Area | What to Plan For |
|---|---|
| Budget | Work out your monthly living costs, relocation expenses and emergency reserves separately. Allow for exchange-rate changes, travel home and rising healthcare costs. |
| Immigration | Identify a suitable route for your age, finances and circumstances. Understand the initial application and the ongoing conditions for staying. |
| Healthcare | Check access to the treatment you need, whether suitable insurance is available and affordable, and which costs you would need to pay yourself. |
| Housing | Consider flexibility, running costs, maintenance and accessibility. Renting initially gives you time to assess a neighbourhood before making a larger commitment. |
| Location and Daily Life | Compare places by transport, climate, hospital access, social opportunities and ordinary daily routines. Consider whether the location would still suit you if your mobility or support needs changed. |
Is Thailand a Good Place to Retire?
Thailand can be a rewarding place to retire if the lifestyle suits you and your finances support it over the long term. The strongest reasons to move usually combine practical advantages with a preference for everyday life here. Lower living costs alone may not compensate for a climate you struggle with, distance from family or difficulty feeling at home.
What Makes Retirement Here Appealing
More flexibility in how you spend your money. Depending on where you come from and how you live, your retirement income may stretch further in Thailand. Housing, local food and everyday services can leave more room for hobbies, eating out or occasional travel. The difference becomes smaller if your lifestyle depends heavily on imported products, expensive accommodation and frequent trips abroad.
A choice of lifestyles and surroundings. You can choose between a large city, an established coastal community, a northern town or a quieter provincial setting. You may also find that your preferred location changes over time. Renting gives you the flexibility to move as your priorities develop.
Opportunities to stay active and connected. Walking, swimming, golf, cycling, language classes and community activities can provide structure beyond working life. Established expat communities offer opportunities to meet people, while learning some Thai broadens your connections beyond them.
Convenience in the right location. Living close to shops, restaurants, transport and suitable medical facilities can make everyday life manageable. The neighbourhood matters as much as the destination: two homes in the same town can offer very different levels of independence and convenience.
The Drawbacks Worth Taking Seriously
- The climate can shape your routine. Heat, humidity, heavy rain and seasonal air pollution can affect how much time you enjoy outdoors. Conditions vary considerably by location and season.
- Staying requires ongoing administration. Immigration, banking and paperwork remain part of life. Procedures can differ between offices and institutions.
- Healthcare needs can change the financial picture. Suitable treatment and a sustainable way to pay for it matter more than the reassurance of having a hospital nearby.
- Getting around is not always straightforward. Uneven pavements and limited public transport can make daily life dependent on driving or taxis.
- Distance from family matters. Visits require time and money, and family circumstances may change how you feel about living abroad.
- A social life takes time to establish. An expat community offers opportunities, but friendships and a satisfying routine still need to develop.
📌 Thailand is more likely to suit you if you enjoy ordinary life here, can accommodate unfamiliar ways of doing things and have some flexibility in your finances. If the move depends on spending the absolute minimum every month, the margin for dealing with setbacks may be too narrow.
How Much Money Do You Need to Retire in Thailand?
The amount you need depends on where you live, whether you rent or own your home, your healthcare arrangements and how you spend your time. A single retiree renting a modest home in Hua Hin will have a different budget from a couple living in central Bangkok or someone renting a pool villa in Phuket.
It helps to separate four things: monthly living expenses, the cost of moving, funds needed for immigration requirements and emergency reserves. Having enough money for one does not automatically cover the others.
Monthly Budgets for Singles and Couples
The following ranges are illustrative planning budgets, rather than minimum income requirements or measured averages. They assume long-term renting, no dependent children and no substantial financial commitments outside the household.
These ranges cover rent, utilities, food, local transport and ordinary leisure spending. Add your actual health insurance premium, medical expenses, international travel, any tax payable and vehicle purchases separately.
| Lifestyle | Single / Month | Couple / Month | Planning Assumptions |
|---|---|---|---|
| Modest | THB 30,000–40,000 | THB 45,000–60,000 | Modest accommodation in a lower-cost neighbourhood, mainly Thai food, limited paid activities and manageable local transport costs. |
| Comfortable | THB 45,000–65,000 | THB 65,000–95,000 | More choice of housing, a mix of Thai and Western food, regular social activities, taxis when needed and some domestic leisure spending. |
| Higher Spending | THB 80,000–120,000+ | THB 110,000–170,000+ | Higher rents or a premium location, frequent restaurant meals, imported groceries, costlier hobbies and more discretionary spending. |
📌 A couple can share rent, internet and some transport expenses, but each person still needs a healthcare budget and travel allowance. Different interests and routines can also affect how much you spend together.
Example Monthly Budget for One Retiree
This illustrative budget assumes one person renting a modest condo or small house in Hua Hin, eating a mixture of Thai and home-prepared food, and maintaining a moderate social life. It assumes no car ownership and limited taxi use. It is a planning example, not my personal spending or a measured average.
| Expense | Monthly Allowance |
|---|---|
| Rent | THB 12,000 |
| Electricity and Water | THB 2,500 |
| Internet and Mobile | THB 1,000 |
| Groceries and Everyday Meals | THB 10,000 |
| Local Transport | THB 3,000 |
| Hobbies and Socialising | THB 5,000 |
| Household and Personal Expenses | THB 2,500 |
| Everyday Living Subtotal | THB 36,000 |
THB 36,000 is the everyday living subtotal, not the complete retirement budget. Add your insurance premium, medical expenses, immigration costs, travel and any tax payable. Relocation costs and emergency reserves remain separate.
Housing location is important to this example: a THB 12,000 rental would need to support your routine without requiring a car or frequent taxi journeys.
What Your Budget Needs to Include
Build your own monthly estimate around these categories:
- Housing: Rent, plus any maintenance or service charges you are responsible for.
- Utilities and communications: Electricity, water, internet and mobile plans. Air-conditioning use can make a substantial difference to electricity spending.
- Food and household shopping: Groceries, restaurant meals, drinking water, cleaning products and personal items.
- Transport: Public transport and taxis, or fuel, insurance, maintenance and repairs if you own a vehicle.
- Healthcare: Your actual insurance premium, medication, routine appointments, dental care and any treatment you expect to pay for yourself.
- Immigration and administration: Applicable application fees, permits, documents and professional help.
- Leisure and travel: Hobbies, memberships, socialising, domestic trips and visits home.
Divide annual expenses by 12 so they appear in your monthly plan, even if you pay them in one instalment. Include continuing expenses in your home country and support for family members where applicable.
For example, THB 40,000 in everyday spending plus THB 120,000 a year in insurance already requires THB 50,000 a month, before international flights or other excluded expenses. That insurance figure is simply an arithmetic example, not a premium estimate.
Moving Costs, Immigration Funds and Emergency Savings
Your relocation budget needs to cover flights, temporary accommodation, rental deposits, initial paperwork and setting up your home. Shipping possessions, buying furniture or purchasing a vehicle can increase the amount considerably.
✅ My guide to how much money you need to move to Thailand explains these initial costs in more detail.
Money held to satisfy immigration conditions should be accounted for separately. Where a route requires a maintained balance, that money may not be freely available for living expenses or emergencies. The visa section explains the relevant distinctions.
Emergency reserves serve a different purpose: paying an unexpected bill, travelling home at short notice or covering a disruption to your income. The appropriate amount depends on your insurance, health, family circumstances and access to other funds.
Making Your Retirement Income Last
If your pension or other income arrives in a foreign currency, calculate what happens when it buys fewer baht. A budget that only works at a favourable exchange rate leaves little room for change.
Review the larger costs periodically, particularly rent, insurance and healthcare. Your spending may also change as you get older, especially if you need more convenient housing, additional transport or help at home.
📌 The useful figure is what your preferred life will cost, with room for foreseeable changes. You can use my Thailand Move Budget Planner to bring monthly expenses, setup costs and a financial buffer into one plan.
Visa Options for Retiring in Thailand
For retirement planning, the important distinction is between a visa that allows you to travel to Thailand and the permission to stay granted by immigration. A visa’s validity date and the date until which you may remain in the country are not necessarily the same.
Your route affects the financial evidence, insurance and ongoing administration involved. The main retirement routes start at age 50, although other options may suit younger retirees.
Non-Immigrant O and Retirement Extensions
One established route is to enter Thailand with a Non-Immigrant O visa based on retirement, usually receiving an initial 90-day stay, then apply for a one-year retirement extension at immigration. Overseas application requirements depend on the embassy or consulate handling your application.
For the standard retirement extension, applicants aged 50 or above generally need to demonstrate one of the following:
- Bank deposit: At least THB 800,000 in a Thai bank account, subject to holding periods.
- Monthly income: At least THB 65,000, supported by acceptable evidence.
- Combination method: Qualifying annual income and a Thai bank deposit totalling at least THB 800,000, subject to the applicable conditions.
Under the deposit method, the published requirements specify THB 800,000 for at least two months before applying and three months after approval. After that, the balance must not fall below THB 400,000, and it must return to the required level before the next application.
The evidence matters as much as the amount. Confirm how your immigration office accepts pension or other income, what bank records it requires and how it handles the combination method before arranging your finances.
📌 These are immigration thresholds, not estimates of what retirement will cost. Meeting a financial requirement does not establish that your income will comfortably cover your preferred lifestyle.
Other Routes: O-A, O-X, LTR and Thailand Privilege
The alternatives serve different circumstances. Some require more documentation or substantially greater financial resources.
| Route | Who It May Suit | Main Considerations |
|---|---|---|
| Non-Immigrant O-A | Applicants aged 50+ arranging a retirement stay through an overseas Thai embassy or consulate. | Can provide a stay of up to one year on entry. Financial evidence, qualifying health insurance, medical documentation and criminal-record clearance are required. |
| Non-Immigrant O-X | Applicants aged 50+ from eligible countries who can meet higher financial requirements. | A five-year stay, potentially extendable for another five years. Nationality restrictions, substantial Thai bank deposits, qualifying Thai insurance and ongoing conditions apply. |
| LTR Wealthy Pensioner | Retirees aged 50+ with substantial qualifying pension or passive income. | A ten-year programme granted in two five-year periods, subject to continued eligibility. Higher income criteria apply, with an investment requirement for applicants in the lower qualifying income band. |
| Thailand Privilege | People willing to pay a substantial membership fee for a long-stay arrangement, including younger retirees. | Membership duration and benefits depend on the package. Compare the upfront fee and conditions with the alternatives; membership does not remove all immigration responsibilities. |
The O-A and O-X routes have distinct insurance and financial conditions, so they should not be treated as longer versions of the same arrangement.
For the LTR Wealthy Pensioner category, the headline qualifying passive income is USD 80,000 a year. Applicants with at least USD 40,000 but less than USD 80,000 need an additional qualifying investment of at least USD 250,000 in Thailand. Health insurance or an accepted alternative is also required.
Thailand Privilege is a paid membership programme rather than a retirement-specific route. Check the current packages directly, as fees, promotions and availability can change.
Ongoing Immigration Responsibilities
Once you are settled, several separate obligations may apply:
- Extensions: A standard retirement extension is normally granted for one year at a time. You must continue to meet its conditions.
- Address reporting: Standard retirement arrangements generally require reporting after 90 consecutive days in Thailand. This report does not extend your permission to stay. LTR holders follow a separate annual reporting system.
- Re-entry arrangements: If you hold a standard retirement extension, obtain a re-entry permit before leaving Thailand to preserve that permission to stay. A re-entry permit retains the existing expiry date; it does not add time. Other routes may include multiple-entry privileges.
- Accommodation notifications: TM30 accommodation reporting is separate from your own periodic address report. Confirm the arrangements with your landlord or accommodation provider.
If you intend to retire before age 50, you will need a different qualifying basis for staying. Thailand Privilege may be an option, while family or other visa categories depend on your circumstances. Repeated tourist entries are not a dependable foundation for a permanent retirement plan.
📌 If you are considering the O-A route, my Non-Immigrant O-A retirement visa guide explains the application process and requirements. Before applying, confirm the current checklist with the Thai embassy or consulate handling your application.
Healthcare and Health Insurance
Healthcare deserves attention early in your retirement planning. The question is whether you can access suitable treatment where you intend to live and pay for it over the long term.
Your existing conditions, insurance options and proximity to specialist care may influence both your budget and your choice of location.
Access to Public and Private Hospitals
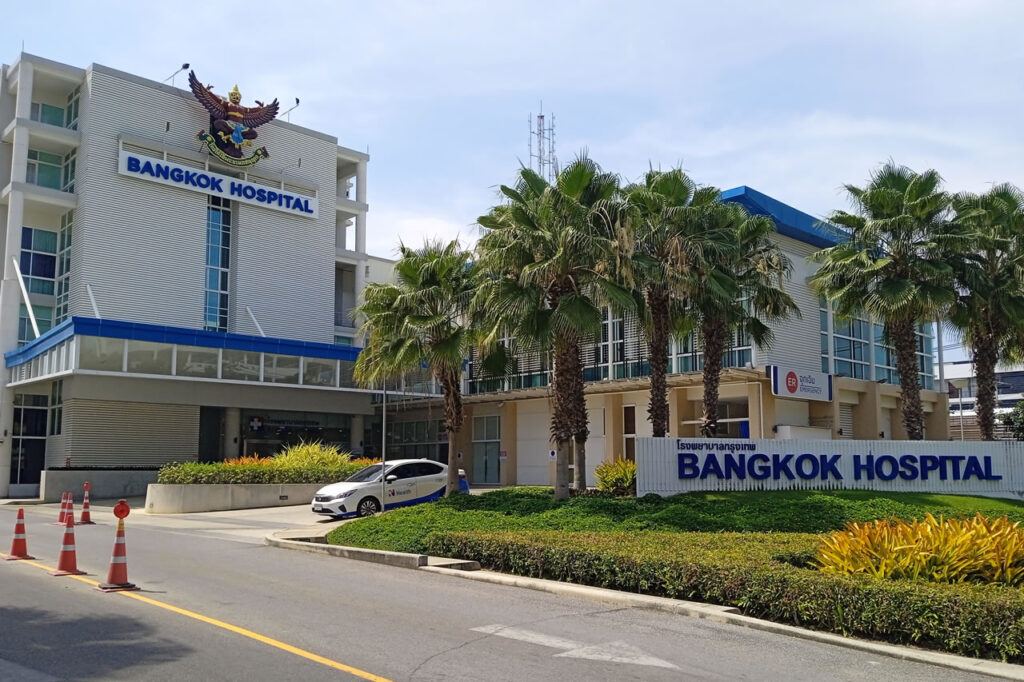
Thailand has both public and private healthcare, with considerable differences between individual facilities.
Public hospitals can provide a more affordable route to treatment. However, busy outpatient departments, longer waits and language barriers may make appointments less convenient. Major public teaching hospitals also provide specialist care, so public healthcare should not be viewed simply as a budget option for minor illnesses.
Private hospitals often offer easier appointment arrangements, English-speaking services and greater comfort. Those conveniences come at a price, particularly for complex treatment, intensive care or a prolonged admission. Private care can be expensive even when individual consultations seem affordable.
When comparing retirement locations, consider the care you are likely to need. A nearby hospital may handle routine appointments but require you to travel elsewhere for a particular specialist or procedure. Repeated journeys can become tiring and expensive.
✅ My guide to the Thailand healthcare system for foreigners explains access, payment and the differences between public and private treatment.
Arranging Insurance as You Get Older
The insurance available to you depends on your age, medical history and the insurer’s terms. An attractive advertised premium does not establish what you personally will be offered.
Before building a retirement budget around a policy, establish:
- Entry and renewal ages: The oldest age for joining and the conditions for continuing cover.
- Medical underwriting: Whether your history results in exclusions, a higher premium or a declined application.
- Coverage limits: The overall benefit limit and any separate restrictions on rooms, procedures or treatments.
- Your share of the bill: Deductibles, co-payments and expenses outside the policy.
- Payment arrangements: Which hospitals offer direct billing and when prior approval is needed.
- Geographical cover: Whether treatment during visits home or other overseas trips is included.
Entry age and renewal age are different. A policy that accepts you today needs to remain suitable and affordable later. Changing insurers can also mean a fresh assessment of your medical history.
Pre-existing conditions need particular attention. Do not assume an ongoing condition will be covered because the policy is described as comprehensive. Obtain written confirmation of any exclusions and how they affect related treatment.
Health insurance requirements depend on your immigration route. The published conditions for a standard retirement extension based on Non-Immigrant O status do not include the mandatory insurance requirement that applies to O-A holders. You still need a workable way to pay for treatment. For an initial visa application overseas, check the insurance requirements with the embassy or consulate handling your application.
✅ For age-specific considerations and representative premium ranges, see my guide to health insurance in Thailand over 60.
📌 If you want help comparing policies, my recommended broker is AA Insurance Brokers. Ask for options based on your medical history, preferred hospitals and budget, including a clear explanation of exclusions and renewal conditions.
Planning for Costs You May Need to Pay Yourself
Even with insurance, you will need to budget for expenses the policy does not cover. These may include routine appointments, medication, dental treatment, deductibles and excluded conditions.
An inpatient-focused policy can reduce premiums compared with broader cover, but check how it handles treatment without an overnight admission. Cancer treatment, scans and day procedures can be classified differently between policies.
If suitable insurance is unavailable or unaffordable, paying directly for care requires a realistic assessment of your resources and treatment options. Being able to afford ordinary appointments does not establish that you could fund a major operation or prolonged illness.
It is also useful to have accessible money while a claim or payment guarantee is being arranged. Direct billing remains subject to approval and policy terms.
📌 A workable healthcare plan combines suitable treatment, a clear understanding of your cover and enough accessible money for your own share of the costs. Review those arrangements as your health, premiums and circumstances change.
Where Are the Best Places to Retire in Thailand?
The best place to retire in Thailand is somewhere your ordinary week works well: suitable housing, manageable journeys, access to healthcare and enough opportunities to enjoy your time.
Start with the type of life you want, then compare neighbourhoods. Living centrally or on the outskirts can make as much difference as choosing between two cities.
The table below gives a broad comparison. Cost descriptions are relative starting points; housing and lifestyle can change the picture considerably.
| Location | Retirement Appeal | Costs and Practicalities | Main Trade-Off |
|---|---|---|---|
| Hua Hin | Relaxed coastal living and an established retirement community. | Moderate costs; local hospitals and everyday services. Transport matters outside central areas. | Less variety and limited flight connections. |
| Chiang Mai | Activities, social opportunities and access to northern countryside. | Broad housing choice, hospitals and an international airport. | Severe seasonal air pollution and increasing traffic. |
| Pattaya and Jomtien | An active international community and extensive coastal amenities. | Wide condo selection, hospitals and shared transport on established routes. | Busy surroundings; noise varies substantially by neighbourhood. |
| Bangkok | City life, specialist healthcare and extensive travel connections. | Wide price range; rail-connected neighbourhoods can support life without a car. | Congestion, noise, heat and air pollution. |
| Phuket | Beaches alongside international services and communities. | Higher spending potential; hospitals and an international airport. | Traffic, tourism pressure and travel between spread-out areas. |
| Koh Samui | Island surroundings with established services and social opportunities. | Budget carefully for transport and journeys off the island. | Limited public transport and potentially less convenient specialist care. |
| Smaller Cities and Rural Areas | Potential housing value, quieter surroundings or proximity to family. | Assess the specific town, transport options and distance to suitable treatment. | Fewer alternatives if your healthcare, mobility or social needs change. |
Hua Hin
Hua Hin suits retirees who want the beach nearby, an established foreign community and a relatively relaxed routine. Shops, restaurants, hospitals and golf courses provide the essentials without the intensity of a large city.
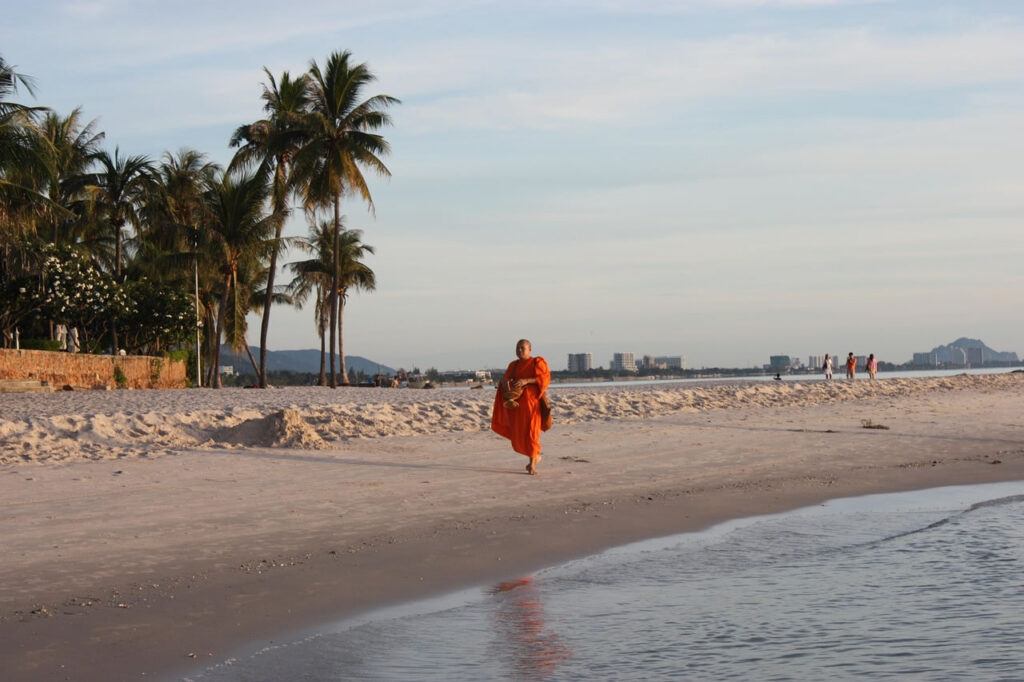
The main decision is where to live within the area. An inland house may offer more space for your money, but daily life can become dependent on driving. Central locations offer greater convenience, usually with less privacy or more activity nearby.
I have found Hua Hin affordable for the lifestyle I want. Its quieter atmosphere suits me, although someone seeking frequent events and a wider social scene may prefer a larger city.
✅ My guide to living in Hua Hin looks more closely at neighbourhoods and everyday practicalities.
Chiang Mai
Chiang Mai offers a broad mix of restaurants, activities, hospitals and social groups, with mountains and countryside within reach. It can suit retirees who want variety and an international community spanning different ages and interests.
Seasonal air pollution is a major consideration. It can affect how freely you use the outdoors and whether you want to remain in the region throughout the year. Cooler winter weather should not distract from the heat and pollution experienced at other times.
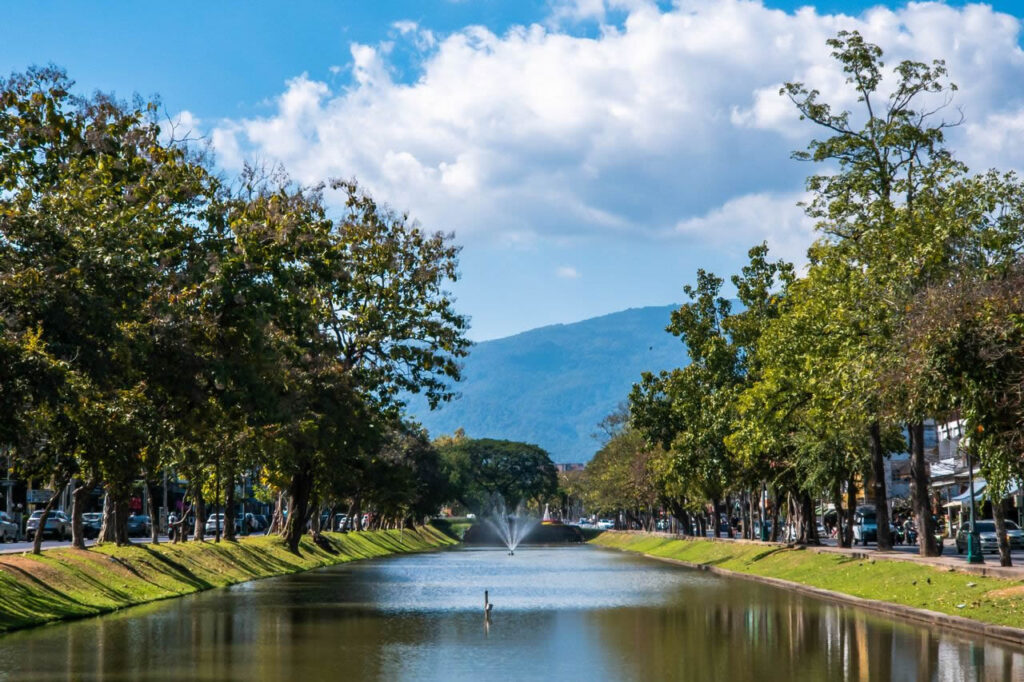
Having lived in both cities, I would not assume Chiang Mai is substantially cheaper than Hua Hin. For comparable lifestyles, my overall costs have been surprisingly similar. Chiang Mai offers more choice; Hua Hin feels easier to manage.
✅ My Hua Hin vs Chiang Mai comparison explores those differences in detail.
After around 25 years in Chiang Mai, I moved to Hua Hin in 2024. Chiang Mai had suited a long chapter of my life, including raising my family and working in property. By the time I moved, I wanted a slower pace and the beach nearby.
Hua Hin gives me the amenities I need, and I find getting around easier. I have fewer choices, but I do not feel that anything important is missing. That is a personal fit rather than a verdict that one city is better for everyone.
Pattaya and Jomtien
Pattaya deserves consideration beyond its nightlife reputation. Its established international community, housing selection, restaurants and medical facilities can make it a practical retirement base.
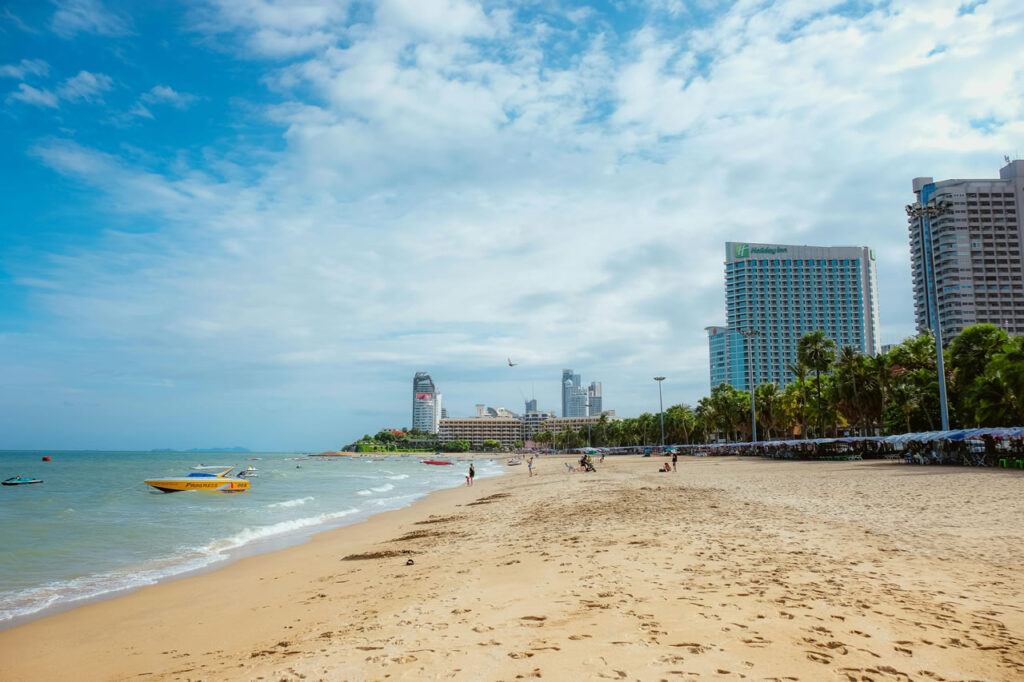
Jomtien, Pratumnak and parts of Naklua offer alternatives to the busiest central streets. However, a quieter district does not guarantee a quiet home: nearby bars, traffic and construction still matter.
It may suit you if you want an active coastal community with plenty of everyday conveniences. Choose the neighbourhood and building carefully, particularly if you are sensitive to noise or expect to rely on shared transport.
Bangkok
Bangkok can suit retirees who enjoy city life, want extensive specialist healthcare options or travel frequently. Living close to rail transport, shops and regular appointments can reduce dependence on driving.
The compromise is the urban environment: congestion, noise, heat and pollution. A convenient condominium may work well, but check the journey from the building entrance to the station or shops, including crossings and pavements.
Phuket and Koh Samui
Phuket and Koh Samui both offer beach settings and established international communities, but the practical differences matter for retirement.
Phuket offers a broader choice of hospitals, shopping and international flights. Its size also means that your home, preferred beach, friends and medical appointments may be some distance apart. Choosing a neighbourhood close to your regular destinations can reduce time spent in traffic.
Koh Samui offers a smaller island setting with established hospitals and everyday services. Public transport is limited, and journeys off the island need to be included in your budget. If you need regular specialist treatment, establish whether it is available locally.
Both can support a comfortable retirement, but compare actual housing and transport costs in your shortlisted neighbourhoods. A visit during the wetter months can also help you assess how much you enjoy the location beyond beach weather.
Smaller Cities and Rural Areas
Places such as Udon Thani, Khon Kaen, Korat or Chiang Rai may also be worth investigating, particularly if you have family connections or prefer a smaller city to the major coastal retirement hubs.
A provincial city and a rural village are very different retirement choices. Assess the actual distance to hospitals, shops and friends, together with how you would manage without driving.
Useful questions include: Who would you spend time with? How would you reach treatment? Would daily life still work if your partner were temporarily unavailable? The answers are more informative than a low advertised rent.
Renting or Buying a Retirement Home
Your retirement home needs to suit your daily life, finances and longer-term plans. Buying can provide stability and the freedom to adapt a property, while renting preserves flexibility and keeps more of your money available for other needs.
Neither choice is automatically better. The important questions are how well you know the area, what rights you would acquire and how easily you could change your arrangements later.
Renting While You Get Established
Renting initially gives you time to discover whether a neighbourhood works beyond the first few weeks. Traffic, noise, drainage, afternoon heat and the convenience of everyday journeys become clearer once you have lived there.
It also allows you to adjust. You may discover that a smaller central home suits you better than a spacious house farther out, or that being close to friends matters more than having a sea view.
Before comparing rents, establish the total monthly cost. Electricity, water, internet, gardening and pool maintenance can change the apparent value of a property. Clarify responsibility for repairs, deposit terms and any restrictions that affect you, such as keeping pets.
✅ My guide to renting a home in Thailand covers the search, rental terms and moving-in checks.
Buying a Condo or Considering Other Arrangements
For an eligible foreign buyer, a condominium can provide freehold ownership in their own name, subject to the building’s foreign ownership quota and the applicable registration requirements. The standard quota is measured by unit floor area, not the number of apartments.
For retirement, the building deserves as much attention as the unit. Management, maintenance, lifts, noise and provision for major repairs all affect whether it will remain a comfortable home. A low purchase price can become less attractive if substantial work is approaching.
✅ My guide to buying a condo in Thailand compares older, newly completed and off-plan properties, including ownership costs and practical checks.
A house requires a different assessment because ownership of the building and rights over the land are separate matters. Foreigners generally cannot own land directly. A lease or another registered right may provide occupation or use, but each arrangement has different limits concerning duration, transfer and inheritance. Paying for a property does not, by itself, establish ownership.
✅ My guide to legal property ownership in Thailand explains those distinctions. Have an independent Thai lawyer examine the proposed arrangement before you commit.
Also consider how much accessible money would remain after buying. Include purchase expenses, furnishing, maintenance and future repairs alongside healthcare reserves. If you later need to move, a sale may take time; avoid making your next step dependent on a quick resale at your preferred price.
Choosing a Home That Will Still Suit You Later
A comfortable retirement home should support independence as your needs change. Features worth considering include:
- Access: Steps, stairs, lift reliability and the route from parking or the street to your door.
- Layout: Whether the bedroom, bathroom and main living space are accessible without climbing stairs.
- Daily journeys: Practical access to groceries, appointments and social activities if you stop driving.
- Upkeep: How much work the house, garden or pool requires, and the cost of help.
- Support: Space for a visiting relative or carer, should that become useful.
Pensions, Banking and Tax
A retirement income needs to do more than cover your expected spending. You also need reliable access to it, suitable banking arrangements and a clear understanding of any tax obligations.
These arrangements depend on where your income comes from, the type of pension or investments you hold and your residence status.
Receiving Your Pension and Transferring Money
Before moving, confirm with your pension provider how living in Thailand affects payments. Check whether it can pay into a Thai account, what charges apply, whether annual increases continue and whether you must periodically provide proof that you are still alive.
For example, UK State Pension recipients living in Thailand do not normally receive the annual increases available to pensioners living in the UK. That can make a substantial difference over a long retirement. Other countries and pension schemes have their own rules.
You may prefer to receive income into an overseas account and transfer money to Thailand yourself. When comparing transfer methods, look at the final baht amount received after fees and currency conversion, together with transfer limits, processing times and the records provided.
If you use overseas income to support an immigration application, confirm the required evidence before choosing your transfer arrangements. A payment reaching your account does not necessarily mean the bank records will demonstrate everything immigration requires.
✅ My Wise review for expats in Thailand explains how the service works and the practical considerations when using it.
If you intend to keep accounts in your home country, confirm that the providers accept customers resident in Thailand. Keep your address and tax-residence information accurate, and check how you will access accounts or replace cards while abroad.
Opening and Using a Thai Bank Account
A Thai account is useful for rent, bills, local transfers and everyday payments. It may also form part of your immigration arrangements.
Plan account opening alongside your visa application and financial timetable. Banks assess foreign applicants according to their documentation and circumstances; do not assume you can arrive as a tourist and immediately open the account you need. Bangkok Bank’s current public guidance directs foreign applicants to contact a branch for its requirements.
Ask the bank what it requires for your particular status, including identification, address evidence and supporting documents. If you will use the account for a retirement extension, confirm with immigration that the account type and ownership arrangements are acceptable.
✅ My guide to opening a Thai bank account as a foreigner covers the process in more detail.
Understanding Your Tax Position
A retirement visa does not automatically make your pension or overseas income tax-free. Immigration status and tax residence are separate matters.
Under Thailand’s general rules, spending 180 days or more in the country during a calendar year makes you a Thai tax resident. Revenue Department guidance states that foreign assessable income arising from 1 January 2024 onward, in a year when you were Thai tax resident, can be taxable when brought into Thailand, including in a later year.
The same guidance distinguishes foreign income earned before 2024 and income earned in a year when you were not Thai tax resident. Consequently, a transfer is not automatically taxable simply because money enters a Thai account. Its source and history matter.
LTR Wealthy Pensioner holders have a separate exemption for qualifying foreign-sourced income brought into Thailand, subject to the applicable conditions. If you use this route, have its specific tax treatment checked rather than assuming the general remittance rules apply unchanged.
Your pension’s treatment may also depend on the relevant double taxation agreement. State pensions, government-service pensions, private pensions and lump-sum withdrawals should not be assumed to receive identical treatment. Treaty provisions may allocate taxing rights or provide relief through a foreign tax credit, subject to conditions. Paying tax overseas does not by itself establish that nothing further is required in Thailand.
Keep records showing pension payments, investment income, transfers, relevant savings balances and tax paid abroad. These help establish where the money came from and support any claim for treaty relief.
Before making substantial transfers or pension withdrawals, obtain advice from a qualified adviser familiar with Thailand and the country concerned. Ask them to establish:
- Your tax residence in each country.
- How each income source is treated.
- Whether treaty relief or a specific exemption applies.
- Whether you need to register or file a Thai tax return.
📌 Base decisions on rules in force when you act. Announced proposals and reports of possible tax changes are not a sufficient basis for moving retirement funds.
Everyday Life in Retirement
Once the practical arrangements are in place, retirement becomes about how you spend your days. Having time, a comfortable home and enough income provides a foundation, but the location also needs to support the routines and relationships you enjoy.
Building a Social Life and Routine
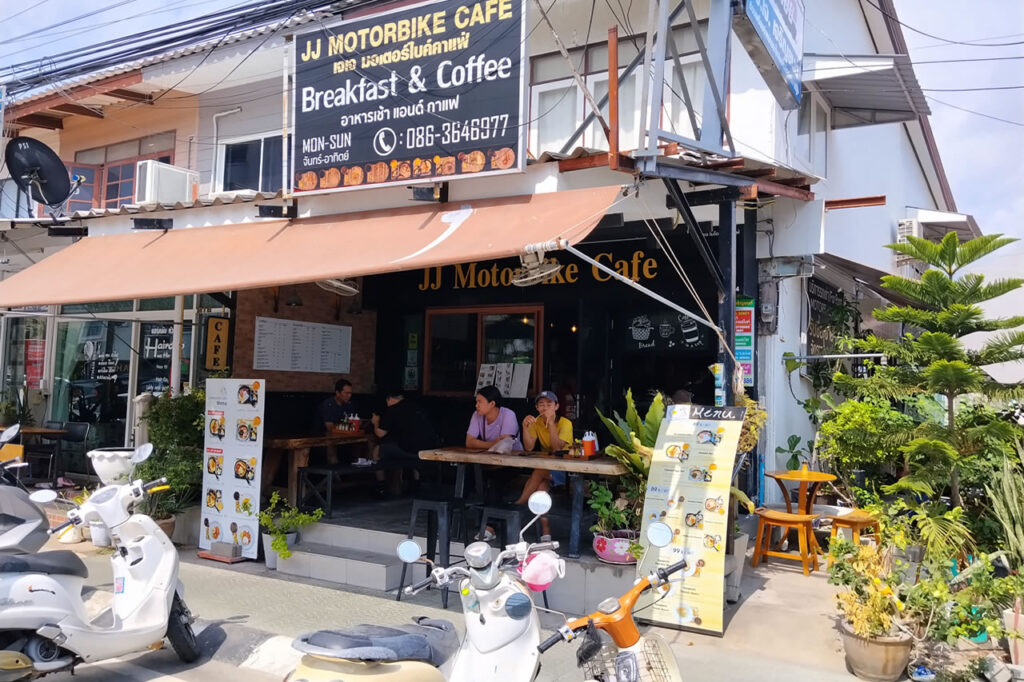
Regular activities can make it easier to establish friendships. A walking group, language class, hobby club or familiar café gives you repeated contact with people, without every meeting needing to become a planned occasion.
An established expat community can help you settle in, but its size matters less than whether it offers activities and people you connect with. Being surrounded by foreigners does not necessarily mean you will find the company you want.
If you are moving alone, consider how easily you could maintain a social life from your intended home. A quiet property outside town may be appealing, but less convenient if every meeting requires a drive.
Couples may also have different expectations of retirement. One person might enjoy spending most days at home while the other wants regular outings. A location that allows each of you some independence can make daily life more satisfying.
There is no need to fill every day. The aim is to have enough structure, company and interests to make your ordinary week enjoyable.
Getting Around
Your transport arrangements affect where you can comfortably live and how much independence you retain.
When assessing a home, consider the journeys you make regularly: shopping, appointments, meeting friends and pursuing hobbies. Test those journeys using the transport you expect to rely on, including the return trip.
Being close on a map does not always mean being easy to reach. A busy road crossing, uneven pavement, steep approach or lack of shade can make a short walk impractical. Equally, a home farther away may work well if reliable transport is available.
If you intend to drive, include the full cost of ownership in your budget and arrange the appropriate licence and insurance. Consider whether the same location would still work if you later preferred to stop driving.
A motorbike should be a personal choice based on your experience and comfort, rather than something your housing location leaves you dependent on.
Language and Cultural Adjustment
How much Thai you need depends partly on where and how you live. English may cover many interactions in an international neighbourhood, while dealing with local tradespeople, neighbours or administrative matters can require more help.
Conversational Thai gives you greater independence and more opportunities to connect with people. You do not need to become fluent before benefiting from it. Being able to explain a problem, ask a follow-up question or understand a simple answer can make everyday situations easier.
I speak conversational Thai but cannot read or write it. That still helps me in daily life, although I need assistance with written information and more complicated matters.
Cultural adjustment also involves learning how people around you communicate and handle situations. Expectations about directness, timing and resolving disagreements may differ from those you are used to. Asking questions and allowing time to understand an unfamiliar process is usually more productive than assuming it should work the same way as at home.
Settling in does not require you to enjoy every aspect of life in Thailand. It means finding an everyday arrangement that suits you and being comfortable with the differences that remain.
Planning for Later Life
Your needs may change during retirement, even if you arrive in Thailand healthy and independent. Having options for care, practical support and a possible move gives you more control if your circumstances change.
When You Need More Help
Support can range from help with shopping and household tasks to personal care, nursing or a move into a residential facility. Thailand has home-care services, assisted-living arrangements and nursing facilities catering to foreign residents, but the level of support varies between providers.
When assessing an option, establish what the quoted price includes and whether the provider can meet your particular needs. Help with meals and housekeeping is different from qualified nursing care or specialist dementia support.
Questions worth asking include:
- What care is available during the day and overnight?
- How are medical appointments and emergencies handled?
- What happens if your needs increase?
- Which services, supplies and treatments cost extra?
- Can staff communicate comfortably with you?
If you have a partner, discuss what support each of you could realistically provide. Caring responsibilities can become demanding, and outside help may be necessary even when both people want to remain at home.
✅ My guide to long-term care options for foreigners in Thailand explains the different arrangements and considerations.
Wills, Emergency Contacts and Important Documents
Someone you trust should know whom to contact and where to find essential information if you become seriously ill. This might include your insurance details, medication list, emergency contacts and the location of important documents.
Being named as an emergency contact does not necessarily give someone authority to manage your money or make decisions for you. Ask a qualified Thai lawyer which arrangements are appropriate if you cannot manage your affairs. Documents prepared overseas may not operate in Thailand as you expect; British government guidance, for example, warns that a UK lasting power of attorney may not be recognised here.
A will addresses a separate issue: what happens to your assets after death. Thai bank accounts, a vehicle or property can make this relevant even if most of your wealth remains overseas.
📌 If you have assets in more than one country, have the arrangements reviewed together so that the documents work consistently. My guide to making a will in Thailand covers the main considerations for foreign residents.
Keeping the Option to Return Home
You may remain happy in Thailand for the rest of your life, or later decide that family proximity, healthcare or familiar surroundings matter more. Keeping that choice financially possible is part of a flexible retirement plan.
Consider what returning would involve beyond the airfare: temporary accommodation, setting up another home, moving possessions and arranging any care you need. Check how residence affects access to healthcare and other services in your home country.
If you have a Thai partner, also establish what permission they would need to accompany you. Your right to return does not automatically settle their immigration position.
How to Prepare for Retirement in Thailand
The main decisions are connected. Your immigration route affects financial arrangements, healthcare needs influence location, and your choice of home shapes transport costs and daily life.
Start by establishing whether the move is financially and practically workable, then use time on the ground to refine the details.
Try Everyday Life Before Committing
A scouting stay is most useful when it resembles the life you expect to lead. Stay in a neighbourhood you could realistically afford, use your intended transport and keep track of ordinary spending.
Alongside exploring the area, try the routines that would form part of your week: buying groceries, attending an activity, reaching a hospital and spending time at home. Visit potential residential areas at different times to assess traffic, noise and convenience.
Give yourself some ordinary days. A full sightseeing schedule can leave little opportunity to discover whether you enjoy living somewhere when there is nothing special planned.
If possible, experience the location outside your preferred holiday season. Where that is impractical, investigate the conditions you will miss, particularly heat, heavy rain and seasonal air pollution.
Use the stay to check assumptions. You may find that your budget needs adjusting, that a different neighbourhood works better or that you want to compare another town before deciding.
A Practical Retirement Checklist
The sequence below brings the main preparations together. Some tasks will overlap, particularly immigration, banking and insurance.
| Stage | What to Establish |
|---|---|
| 1. Define Your Priorities | Identify the lifestyle you want, your healthcare needs, family commitments and whether you intend to live in Thailand throughout the year. |
| 2. Establish Financial Feasibility | Check pension arrangements and build separate allowances for monthly spending, relocation, immigration funds and emergencies. Review your tax position. |
| 3. Confirm Your Immigration Route | Confirm eligibility, supporting documents, financial timing and ongoing conditions. Establish separate arrangements for an accompanying partner where needed. |
| 4. Check Healthcare Arrangements | Obtain insurance terms based on your medical history, assess uncovered costs and identify suitable treatment providers in your shortlisted locations. |
| 5. Test Your Shortlist | Spend time in realistic residential areas. Test daily journeys, social opportunities and spending, then adjust your plan using what you learn. |
| 6. Prepare the Move | Coordinate applications, insurance start dates, accommodation and travel. Prepare medical records and important documents, and confirm banking access at home and in Thailand. |
| 7. Settle In and Review | Complete the relevant local arrangements, establish routines and compare actual spending with your budget before making larger commitments. |
✅ For more detailed preparation, use my moving to Thailand checklist.
You do not need to decide every aspect of retirement before arriving. The aim is to have the essentials in place and enough flexibility to make informed choices once you are living here.
Frequently Asked Questions
📌 Can I Retire in Thailand Before Turning 50?
Yes, but you need a suitable immigration route other than the standard retirement categories, which start at age 50. Thailand Privilege may be an option, while family or other routes depend on your circumstances. Having enough savings to stop working does not itself qualify you for permission to live in Thailand.
📌 Can My Spouse Accompany Me If Only One of Us Qualifies?
Potentially. A legally married spouse may qualify for a dependent arrangement, including where they are under 50. However, eligibility depends on the principal applicant’s immigration route and the application being made.
For example, Ministry of Foreign Affairs guidance provides for an accompanying spouse who does not qualify for O-A to be considered for a Non-Immigrant O visa. Confirm both partners’ entry and extension arrangements before applying; permission is not automatically shared between spouses.
📌 Can I Split My Retirement Between Thailand and My Home Country?
Yes, provided your immigration arrangements support your travel pattern. If you hold a retirement extension, a re-entry permit preserves the existing permission to stay when you travel abroad; it does not extend its expiry date.
You also need to consider insurance coverage in both countries and how the number of days spent in each affects tax residence.
📌 Does a Retirement Visa Lead to Permanent Residence?
It does not automatically become permanent residence, regardless of how many times you renew it. Permanent residence requires a separate application and satisfaction of its own eligibility criteria. Do not assume that years spent on retirement extensions alone establish eligibility.
📌 Can I Work While Staying in Thailand on a Retirement Basis?
Standard Non-Immigrant O retirement and O-A arrangements do not permit employment. If you intend to work, run a business actively or undertake paid projects, establish the appropriate immigration status and any required work authorisation first.
Do not assume an activity is permitted simply because it is part-time, online or paid overseas. Describe the actual activity when seeking advice.
💬 Are you planning to retire in Thailand, or already living here? Share your questions or experience in the comments below.
Thank you for going into such detail regarding options for retirees. You have been very thorough and has opened my eyes to some of the issues to look out for before moving to Thailand and some of the requirements. One question. For someone in the mid fifties, where would you recommend moving to? Also would you recommend renting before buying a condo?
Hi John, thank you for your feedback, much appreciated! I am glad you found the information useful. To your questions:
Where to move to?
Where to settle depends on your personal preferences as well as the available budget. There are many things to consider. Do you like beach living, city life, or maybe you prefer the countryside? In any case, I would recommend spending several months first at the place you choose before you commit. That gives you enough time to check out everything that is important to you, such as shopping, entertainment, medical care, the expat community, access to nature, and outdoor activities, to name a few.
Rent before buying?
I strongly advice against buying before renting! Rental properties in Thailand are very reasonable priced compare to the Western world and not too difficult to find (with the right information and some effort). If you buy right away and later down the road, find out you would prefer living somewhere else in Thailand, owning a property can be a drawback. Rent first for a while and if you are happy where you are you still can buy.
For information regarding renting read my guide: How to Rent a Condo or House in Thailand: Everything Expats Need to Know