Buying a property in Thailand involves several decisions beyond finding a home you like. What you will legally acquire, the condition of the property, the contract terms and the arrangements for payment all shape how the purchase comes together.
During my years running a real estate agency and working in property development in Chiang Mai, I saw the buying process from several sides. That experience taught me the value of assessing the property and the transaction together. A home can suit your needs perfectly, but the purchase terms still need to work for you.
This guide takes you through the process, from setting a budget and viewing properties to legal checks, contracts, transferring funds and completing the handover. It covers the main differences between buying a condo and acquiring a house with rights over the land, with links to more detailed guides where useful.
Decide What You Want to Buy and Why
How you intend to use the property will shape your search. A home for everyday living, a holiday base and a rental investment may lead you towards different locations, property types and budgets.
For a main home, consider how the property fits your normal routine. Access to shops, healthcare and friends may matter more over time than facilities you enjoyed during a short holiday. If you are unfamiliar with the area, renting there first gives you time to experience the neighbourhood before committing to a purchase.
For a holiday home, think about how often you will realistically visit and who will look after it while you are away. A condo may be easier to manage between visits, while a house offers more space but usually involves more responsibility for maintenance and security.
For a rental investment, assess demand for the type of tenancy you intend to offer. Compare similar properties and allow for vacant periods, management fees, repairs and replacement furnishings when estimating income. If the purchase depends on rental returns, those figures deserve as much attention as the property itself.
You may have more than one purpose in mind, such as occasional personal use followed by retirement later. In that case, decide which purpose takes priority. That makes it easier to judge compromises rather than expecting one property to meet every possible future need.
📌 Also consider how long you expect to keep it. Purchase and selling costs, together with the time needed to find a buyer, matter more if your plans could change within a few years.
Understand What You Will Legally Acquire
Before comparing prices or negotiating a purchase, establish what will be registered in your name. Properties advertised to foreign buyers can involve quite different rights, even when the homes themselves look similar.
A freehold condominium allows you to own the unit in your own name, subject to the Condominium Act’s eligibility requirements. Foreign ownership is generally limited to 49% of the total floor area of all units in the condominium, so availability within that quota needs to be confirmed.
A leasehold property gives you the right to use the property for an agreed period. You are acquiring a lease rather than permanent ownership. When comparing listings, establish whether the offer involves a new lease or the remaining term of an existing one, and have any renewal promises assessed separately.
A house with separate building ownership requires a closer look at both the house and the land arrangement. Foreigners can own a building separately from the land, but ownership of the house does not itself establish the right to occupy the land beneath it. The documents need to address both aspects.
These differences affect how you assess the price, your future use of the property and the options for selling or passing it on. Ask for the proposed ownership and registration documents early, so your lawyer can confirm exactly what the transaction offers.
📌 For a fuller explanation of land restrictions, leases, separate building ownership and registered rights, see my guide to Property Ownership in Thailand for Foreigners.
Set Your Budget and Arrange Funding
Set a total budget that covers the purchase and the amount needed to make the property ready for use. This gives you a more useful spending limit than the asking price alone.
Allow for three groups of costs:
| Cost Group | What to Include |
|---|---|
| Purchase and registration | Agreed price, your share of taxes and transfer or registration fees, legal fees and any inspection costs |
| Initial work and setup | Repairs, renovations, furniture, appliances and utility arrangements |
| Ongoing ownership or occupancy | Building or estate charges, maintenance, insurance, utilities and management costs if you will be away |
The amounts will depend on the property and the agreement. An older home may leave room in the purchase budget but need immediate work, while a furnished property may still require replacement air conditioners or appliances. For a condo or managed estate, request the current charges and details of any planned major expenditure.
📌 Keep a reserve beyond the costs you can already identify. Spending your entire available budget on the purchase leaves little flexibility for repairs or changes after moving in.
Confirm How You Will Pay
If you need financing, establish what is available to you before paying a deposit tied to a purchase deadline. Base your search on confirmed borrowing terms and available funds.
If your money is held overseas, exchange rates and transfer costs will affect the final amount in baht. A budget that works at today’s rate may need adjusting before completion, particularly when payments are spread over several months.
Before moving the purchase funds, coordinate the payment route and supporting documents with your lawyer and the receiving bank. The requirements for a foreign freehold condo purchase deserve particular attention; these are covered in the transfer section below.
📌 At this stage, the aim is to know how much you can spend, when the money will be available and how much you will retain after completion.
Find and Assess Suitable Properties
Online listings are useful for building a shortlist, but they give only a partial picture of the local market. You may find the same property advertised by several agents at different prices, alongside listings that are no longer available. Confirm the current asking price and availability before arranging a viewing.
Compare properties within the same building, estate or immediate area where possible. Differences in usable space, condition, outlook, furnishings and ongoing charges can explain a substantial price gap. Advertised prices show what sellers are asking; they do not establish what comparable properties have actually sold for.
Look Beyond the Property Itself
Use the first viewing to assess whether the home deserves further investigation. Pay attention to the layout, natural light, ventilation, privacy and signs of maintenance problems. Consider how much work would be needed to make it suitable for you, rather than judging it only as presented.
The surroundings deserve a separate visit. Return at a different time of day to get a better sense of traffic, noise and access. Nearby restaurants, entertainment venues, schools or construction sites may have little effect during one viewing and a considerable effect at other times.
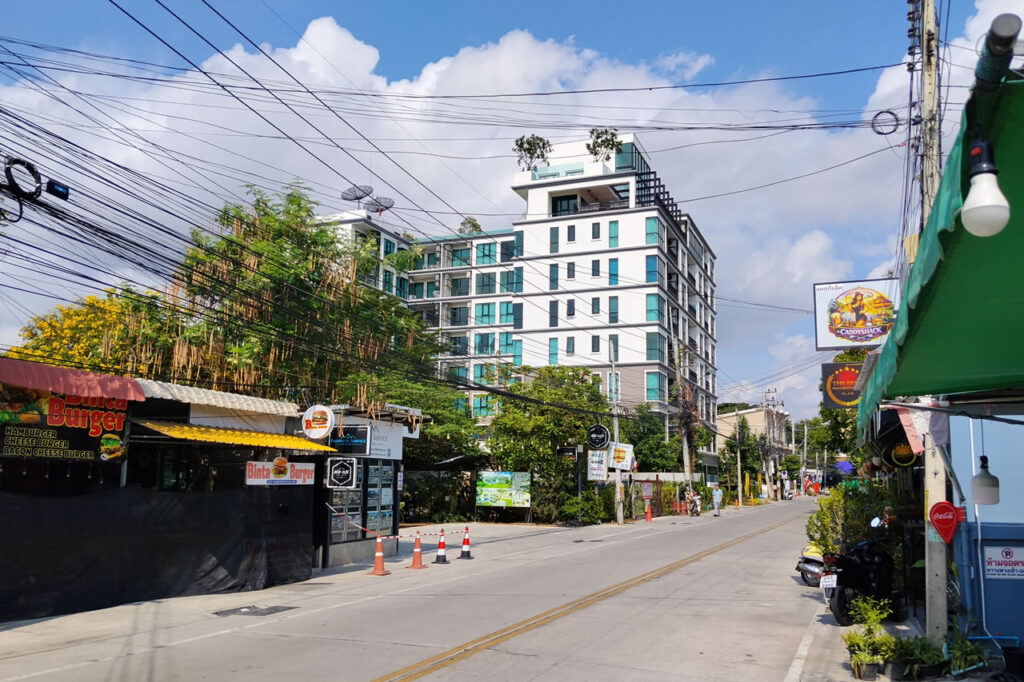
For a house, look at the access road, drainage, boundaries and neighbouring plots. For a condo, spend time in the common areas and look at how the building is maintained. A well-presented unit and a well-managed building are separate considerations.
📌 For a more detailed look at older, newly completed and off-plan units, building management and viewing checks, see my guide to Buying a Condo in Thailand.
Understand the Agent’s Role
A useful agent can arrange viewings, explain local availability, communicate with the seller and help negotiate terms. Ask whom they represent, how they are paid and whether any fee will be charged to you.
Keep the property search and the independent checks as separate tasks. The agent can help obtain documents and answers, while your lawyer reviews the legal position and an inspector or engineer assesses the physical condition where needed.
Once you have a serious candidate, request the relevant documents and a breakdown of ongoing charges. That allows you to assess the property, the proposed transaction and the likely total cost together before making a financial commitment.
Appoint an Independent Lawyer and Carry Out Checks
Once you have identified a property you want to pursue, involve an independent Thai lawyer with experience in the relevant type of transaction. Give them the proposed terms and available documents before signing a reservation agreement or paying a deposit.
Agree on the scope of their work and the fee. Ask whether it includes title searches, contract review, preparation of any lease or other registered rights, and representation at completion. Also confirm who will handle the work and explain the findings to you.
Check the Legal Position
The checks will depend on what you are acquiring, but should establish:
- The seller’s identity and authority: whether the person or company offering the property is entitled to complete the transaction.
- The title and registered interests: what the title covers and whether mortgages, leases or other rights affect it.
- The proposed registration: whether the ownership or rights offered can be registered in your name.
- Access and boundaries: particularly for houses, whether access is legally secured and the property shown matches the title information.
- Building documents and permitted use: whether the relevant approvals support the existing property and your intended use.
- Outstanding obligations: any unpaid charges, existing tenancy or other commitments that need to be resolved.
For a condo, this includes confirming foreign quota availability where applicable and obtaining the necessary information from the condominium management. For a house with a land lease or separate building ownership, the review needs to cover how those arrangements work together.
📌 Ask your lawyer to explain any issue in practical terms: what it means for your use of the property, whether it can be resolved and what must happen before payment or completion.
Assess the Physical Condition Separately
Legal due diligence and a property inspection serve different purposes. A title search will not establish whether a roof leaks, electrical work is safe or alterations have caused structural problems.
For a house, an older property or a home with substantial alterations, consider an independent inspection by a suitably qualified professional. For a new property, a defects inspection can identify work to be completed before handover.
Where the checks identify repairs or missing documents, agree how they will be addressed and record that in the purchase terms. Some findings may justify a price adjustment; others need to be resolved before the transaction proceeds.
Agree the Price, Deposit and Contract Terms
Once you have enough information to proceed, negotiate the full terms of the purchase. Alongside the price, agree what is included, when payments are due, who pays the transaction costs and what needs to happen before completion.
Furniture, appliances, parking arrangements and promised repairs should be identified clearly. An inventory with photographs can help establish what will remain in the property and its agreed condition.
Reservation Agreements and Deposits
A seller or developer may ask for a reservation payment to take the property off the market while the contract and checks are completed. The amount and conditions vary, so establish what the payment commits each party to before transferring it.
Have your lawyer review:
- The property and parties: exactly what is being reserved and who is receiving the money.
- The reservation period: how long the seller will hold the property and when the next decision or payment is due.
- Refund conditions: what happens if the legal checks reveal a problem, the proposed registration cannot proceed or the seller withdraws.
- Treatment of the payment: whether it forms part of the purchase price and how receipt will be acknowledged.
If checks are still underway, the agreement should identify the conditions that must be satisfied for you to proceed. A general assurance that the deposit is refundable leaves room for disagreement about the circumstances.
The Sale and Purchase Agreement
The main contract should bring the agreed terms together, including the payment schedule, completion date, allocation of taxes and fees, included items and any conditions still to be fulfilled. It should also address what happens if either party cannot complete as agreed.
For a property under construction, additional attention is needed for the specifications, staged payments, completion deadline, handover requirements and arrangements for defects. Payments made during construction create a different exposure from paying for an existing property at transfer.
You should be able to understand the contract you are signing. Where Thai and English versions are used, have your lawyer check that they are consistent and explain which version governs if the wording differs.
📌 Before signing, confirm that the final documents reflect the negotiated agreement, including any changes made through the agent or directly with the seller.
Prepare the Funds and Transfer Documents
Before arranging the final payment, have your lawyer confirm the documents required for your transaction and who will provide them. Coordinate this with the receiving bank and the seller so there is time to resolve missing paperwork before the completion date.
Transferring Funds for a Foreign Freehold Condo
For many foreign buyers, eligibility to acquire a freehold condo depends on evidence of qualifying purchase funds. The usual route is to send foreign currency into Thailand and obtain supporting documentation from the receiving Thai bank. The documented amount must cover at least the purchase price. Other qualifying routes exist, including certain foreign-currency and non-resident baht account arrangements, so confirm which applies to you.
Before sending the money, ask the receiving bank to confirm:
- The account and currency to use.
- How the buyer’s name and purpose of payment should appear.
- What evidence it will issue for registration at the Land Office.
- What documents it needs from you to prepare that evidence.
You may hear the bank evidence referred to as a Foreign Exchange Transaction form, or FET form. Depending on the transaction, a bank certificate or other supporting confirmation may be used. Have your lawyer and bank confirm the appropriate documents rather than assuming that an ordinary transfer receipt will be sufficient.
Choose the transfer route with these requirements in mind. A service that works well for everyday living expenses may produce different records from a direct international bank transfer. Confirm that the required evidence can be obtained before moving the purchase funds.
Assemble the Completion Documents
The paperwork varies according to the property, the parties and the rights being registered. It may include passports and identity documents, title documents, company or marital-status documents, bank evidence and powers of attorney where someone is acting for a party.
For a condo transfer, the seller will also need to coordinate documents from the condominium juristic person, including confirmation of the foreign ownership proportion where applicable and a debt-free certificate confirming that the unit’s common-expense obligations have been settled.
Ask your lawyer to check the complete set before the appointment, including names, property details and any translations or certifications required. Keep copies of the contracts, payment records and bank evidence together; they form part of your record of the purchase.
Complete the Transfer and Handover
Before completion, confirm that the agreed conditions have been met, the documents are ready and everyone understands how payment, registration and possession will be coordinated. Your lawyer should explain the sequence for your particular transaction, including any arrangements to discharge an existing mortgage.
Inspect Before Releasing the Final Payment
Arrange a final inspection as close to completion as practical, while there is still time to address any discrepancy. Check that the property is in the agreed condition, included items remain in place and promised repairs have been completed.
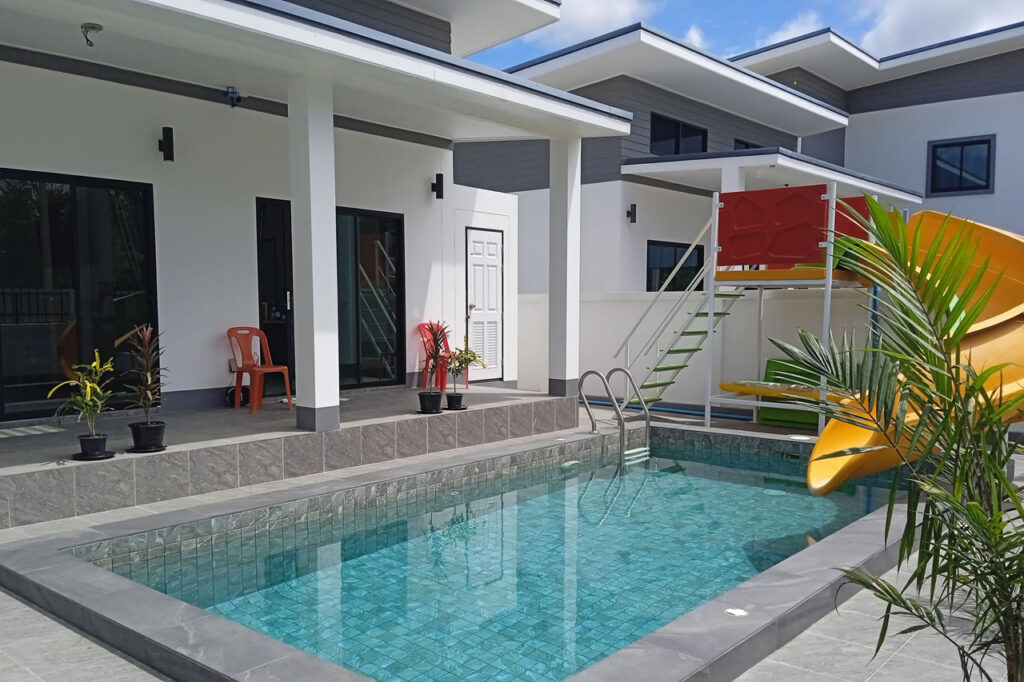
If the property is being sold with vacant possession, confirm that the occupants have moved out or that their departure is coordinated with the handover. If you are taking over an existing tenancy, check that the tenancy documents, deposit and rent arrangements are accounted for.
For a newly completed property, follow up on the defects list and record any outstanding work, the completion deadline and the agreed arrangements for access.
Coordinate Payment and Registration
Agree the final payment method in advance. If cashier’s cheques are being used, confirm the exact amounts and payee names before the bank issues them. Your lawyer should also provide a completion statement showing the balance payable, deposits already paid, taxes and fees, and any agreed adjustments.
At the Land Office, the parties or their authorised representatives complete the relevant registration formalities. Payment and registration need to follow the agreed sequence, particularly where part of the money will repay the seller’s lender.
Before leaving, have your lawyer confirm that the completed registration reflects what you agreed to acquire and that you receive the relevant original documents.
Take Over the Property
The handover should cover more than the front-door key. Collect the access cards, remotes, appliance information, warranties and relevant management contacts. Record electricity and water meter readings and settle how charges up to the handover date will be divided.
For a condo or managed estate, notify the management office and arrange billing and access records. Confirm which utility accounts need to be transferred, closed or opened in your name.
Keep the registered documents, signed contracts, receipts and handover record together. They will be useful when managing the property and if you later sell or transfer your interest.
Taxes, Fees and Other Purchase Costs
The amount payable at completion depends on the transaction, the seller’s tax position and how you have agreed to divide the costs. Ask for an itemised estimate during negotiations so you can assess the total purchase cost before signing.
The table below summarises the main charges associated with an ownership transfer. These are standard rates; any reduction or exemption needs to be checked against the circumstances of the transaction.
| Charge | Standard Calculation | What to Clarify |
|---|---|---|
| Transfer fee | Generally 2% of the official appraised value | How the fee will be divided between buyer and seller |
| Specific business tax | Where applicable, 3.3% of the higher of the sale price or official appraised value | Whether the sale is subject to this tax or qualifies for an exemption |
| Stamp duty on the sale | Generally 0.5% of the higher of the sale price or official appraised value | Normally payable where specific business tax is not payable |
| Withholding tax: individual seller | Calculated using the official appraised value, applicable deductions and holding period | Obtain a transaction-specific calculation |
| Withholding tax: company seller | Generally 1% of the higher of the sale price or official appraised value | Confirm the seller’s status and calculation |
| Legal and inspection fees | Based on the agreed scope of work | Whether quotations include searches, contract preparation, registration attendance and additional expenses |
📌 The transfer fee and taxes use different calculation rules. The official appraised value is an administrative valuation and may differ from the agreed purchase price; it is not a substitute for assessing the property’s market value.
Agree Who Bears Each Cost
Distinguish the seller’s tax obligations from the costs you agree to bear under the contract. A negotiated arrangement may affect your total outlay, so the agreement should identify each charge rather than simply refer to “shared transfer costs.”
📌 Ask for the amounts in baht as well as the allocation. This makes it easier to compare offers and avoids discovering at completion that the parties understood the arrangement differently.
Lease Registration and Other Rights
A lease involves different charges from an ownership transfer. Lease registration generally attracts a fee of 1% of the total rent over the registered term, with lease stamp duty generally equivalent to 0.1% of the total rent and any key money. Have the calculation confirmed where an upfront premium or other payment forms part of the arrangement.
📌 If the transaction also involves separate building ownership, superficies or another registered right, request a breakdown for each element.
Allow for Property-Specific Payments
For a new condo, the developer may collect a sinking fund contribution, advance common charges and other setup payments at handover. For a resale, clarify outstanding charges and any adjustment for amounts the seller has paid in advance.
These payments are separate from the government transfer charges. Include them in the completion estimate, together with bank charges and any remaining professional fees, so you know the full amount needed to complete.
Plan for Resale, Rental or Inheritance
Your plans may change during ownership. Before buying, consider how the property would work if you moved elsewhere, wanted rental income or needed to pass your interest on to family.
Selling Later
When I worked in real estate in Chiang Mai, I regularly encouraged clients to consider resale, even when they were building what they expected to be their permanent home. Circumstances can change, and a property that appeals to a wider range of buyers gives you more options if you later need to sell.
Among the buyers I dealt with, bungalows were often preferred to two-storey houses, and three bedrooms broadened the appeal compared with two, even where the owners themselves needed less space. An attractive outlook and a generously sized covered terrace were also features buyers valued.
These considerations apply when choosing an existing home too. Your own needs come first, but where two properties suit you equally well, the one with broader appeal may put you in a better position when it is time to sell.
Look at competing listings and how long similar properties have been advertised. Asking prices alone offer limited evidence of resale prospects. Allow for selling expenses and the possibility of a longer marketing period when deciding how much money to commit.
For a leasehold property, have your lawyer explain the provisions for transferring the lease, including any consent requirements and charges. The remaining term will also matter to a future buyer.
Renting It Out
If you may rent the property, check that your intended use is compatible with the applicable law, building or estate rules and any lease conditions. Establish this before relying on rental income in your budget.
Consider who will find tenants, handle repairs and inspect the property if you live elsewhere. Management fees, vacant periods and replacement furnishings affect the return, while rental income may also create tax obligations.
A property that suits you personally may attract a different rental market from the one you initially had in mind. Assess demand for its actual location, size and condition.
Passing Your Interest On
Ask your lawyer what would happen to your particular ownership or registered rights on death. Freehold ownership, leases and personal rights can have different consequences, and an inheritance clause should be reviewed alongside the underlying legal arrangement.
If providing for a spouse or children is part of the purchase decision, address that during the legal review. Discuss whether a Thai will is appropriate and how it should coordinate with any existing estate arrangements overseas.
📌 Keep your family or executor informed about where the relevant documents and professional contacts can be found.
Related Property Guides
- ✅ Property Ownership in Thailand for Foreigners
The legal options for condos, houses and land-use rights, including their limitations and inheritance considerations. - ✅ Buying a Condo in Thailand
Comparing older, newly completed and off-plan units, assessing the building and understanding ownership costs. - ✅ How to Rent a Condo or House in Thailand
A practical guide if you would like to rent before buying or explore an area before making a longer commitment.
💬 Are you considering buying property in Thailand, or have you already been through the process? Share your questions or experience in the comments below.
Thanks Stephan, very useful information
Thanks for reading—I really appreciate your feedback! I aim to make these complex topics clearer for fellow expats. If you’re exploring property seriously, have a look at my guides on Legal Property Ownership in Thailand and Banking & Financial Tips for Expats—both tie directly into the buying process. And if you have specific questions about property types or the steps involved, feel free to ask—I’m here to help.